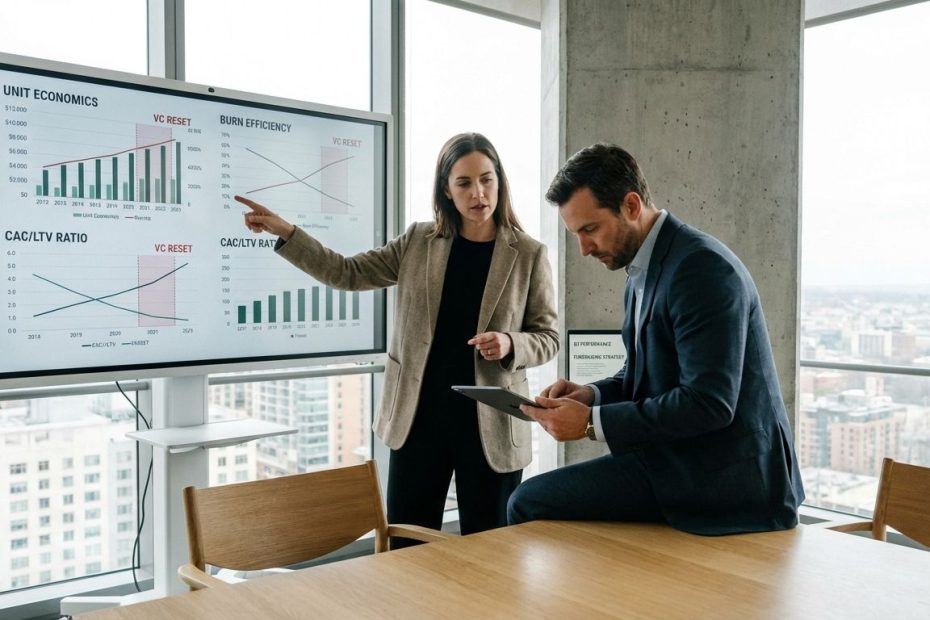
“Growth at all costs” is dead because capital now prices risk like it matters again. You can still grow fast, but you must prove the growth is efficient, repeatable, and tied to real unit economics, not just a pitch narrative.
You’re operating in a market where VC fundraising shrank, LP expectations tightened, and mega-rounds moved to a smaller circle of winners. You’ll leave with a practical playbook: how to position your metrics, how to choose your financing path, and how to run your company so the next fundraise is a process, not a scramble.
Is “Growth At All Costs” Actually Dead In 2026, Or Just More Expensive?
It’s dead as a default strategy. You can still pursue breakout growth, but you must justify the spend with measurable efficiency and a believable route to liquidity.
Start with what changed on the supply side. U.S. venture-capital fundraising fell 35% in 2025 to $66B, a steep drop that also landed about 70% below 2022’s record, with commitments flowing toward firms LPs already trust. That forces more companies to compete for fewer “fresh” VC dollars, and it raises the proof bar across the board.
The practical impact shows up in how partners talk in partner meetings and IC memos. “How big can it get?” is still on the page, but it sits next to “How efficiently can it get there?”, “What breaks at scale?”, “What’s the margin shape?”, and “What is the exit path if public markets stay selective?”
If your plan depends on permanent access to cheap capital, it fails basic underwriting in 2026. If your plan shows disciplined burn, rising gross margin, strong retention, and sales efficiency that improves as you scale, the market still funds you.
Why Are VCs Raising Less Money If Startup Funding Looks Strong In AI?
Because LPs don’t grade VCs on headlines, they grade them on distributions. When exits slow or move later, LPs recycle less cash into new commitments, and fundraising tightens even if deal activity looks busy.
That mismatch explains the weirdness founders feel: “People keep saying the market is back, but my round is taking longer.” You’re not imagining it. A meaningful amount of capital is still being deployed, but it’s being deployed into fewer companies, with tighter requirements and heavier concentration at the top end of the market.
KPMG’s Venture Pulse captured the shape of this cycle: global VC investment stayed strong through 2025, with larger average deal sizes and fewer deals as investors focused on fewer, larger opportunities. KPMG also flagged global VC fundraising as exceptionally weak at year-end 2025, even as investment activity remained elevated.
So you’re dealing with two different markets at once. One is the market for capital formation (fundraising by venture firms), where LP caution dominates. The other is the market for capital deployment (checks into companies), where a small set of categories, especially AI infrastructure and proven AI leaders, pulls in outsized dollars.
What Numbers Prove The “Great VC Reset” Is Real?
You can see the reset in three places: VC fundraising compression, capital concentration, and the widening gap between “hyped growth” and “financeable growth.”
Fundraising compression: U.S. venture-capital firms raised $66B in 2025, down 35% year over year, and far below the peak. Globally, S&P Global Market Intelligence reported $86.7B raised as of Nov. 30, 2025 using Preqin data, marking the first time the global total fell below $100B since 2015. That matters because fewer new funds means fewer new lead checks, fewer experiments, and more follow-on reserved for existing winners.
Concentration: Crunchbase reported $274B invested into U.S.-based companies in 2025, representing 64% of global startup funding. Crunchbase also reported roughly 50% of global venture funding went into AI-related fields, with $211B into AI in 2025. That level of concentration changes your strategy: category selection and positioning can matter as much as fundamentals, especially at Series B and beyond.
Deal size inflation with deal count pressure: KPMG reported $138.1B of global VC investment in Q4 2025 across 7,981 deals and described average deal sizes rising as investors focused on fewer, larger opportunities. That’s a defining feature of this reset: you don’t win by being “fundable” in a general sense, you win by being one of the few opportunities a partner wants to anchor their quarter around.
Is The VC Market Now A Barbell Where Mega-Deals Win And Seed Gets Squeezed?
Yes, and you must adapt based on where you sit on the barbell. The top end of the market gets headline rounds, sometimes at valuations that look disconnected from near-term cash flow. The bottom end can still raise, but it takes stronger proof, tighter storytelling, and better founder discipline around burn.
The middle is where it gets uncomfortable: companies that are not tiny and not dominant. If you’re in that middle zone, investors will ask harsher questions: “Why hasn’t this inflected yet?”, “What is the bottleneck?”, “If the product works, why isn’t distribution compounding?”, “What happens if this takes 24 months longer than the plan?”
Capital concentration into AI amplifies the barbell effect. Crunchbase’s 2025 data points to AI taking about half of global venture dollars. KPMG’s Q4 2025 reporting highlights multiple $1B+ megadeals and emphasizes that many occurred in the United States, reinforcing how the largest checks cluster around a narrow set of themes and geographies.
Seed is not “dead,” but the pricing of seed risk shifted. Many funds now treat seed like a small Series A: sharper ICP, clearer evidence of retention, early proof of distribution, and an operator-grade plan to manage burn if growth comes in below plan.
What Metrics Replaced “Growth At All Costs” In Investor Decision-Making?
You still get rewarded for growth, but only when it’s paired with control. That means the market cares less about raw topline acceleration and more about the quality of your revenue, the efficiency of your spend, and how quickly the business can reach durability.
Expect investors to anchor on a tighter set of operational measures: gross margin, contribution margin, net revenue retention (or cohort retention for usage-based products), CAC payback, sales efficiency, burn multiple, and credible assumptions on pricing and churn. If you run a marketplace or a consumer product, they will translate the same discipline into take rate, repeat rate, cohort margin, and cost to reacquire.
In 2026, the most financeable model is the one that can tighten quickly under pressure. That means you have clear levers: pricing that can move without breaking demand, marketing spend you can reduce without collapsing pipeline quality, and a product roadmap that can narrow without losing the customer’s “must-have” job.
The reset also changed how investors interpret your plan. A deck that claims “we’ll figure out monetization later” or “we’ll optimize unit economics after we scale” reads as avoidable risk. A deck that shows a tight feedback loop between spend and payback reads as leadership.
How Do You Raise In 2026 Without Getting Trapped By Valuation, Burn, Or Terms?
You raise by treating the round as a proof exercise, not a persuasion exercise. You show that the business can produce repeatable outcomes, and you show that leadership can make hard tradeoffs early, not after the bank balance forces it.
Start with the main mistake many teams make: building a plan that requires a perfect market. A 2026 plan must survive slower sales cycles, procurement delays, and changing budget priorities. If you can’t show how the company stays in control under those conditions, investors assume the next round will be reactive.
Then tighten your fundraising posture around three deliverables that reduce perceived risk:
- A metric story that matches your stage (retention and payback early, margin and scale efficiency later).
- A capital story that explains what this round buys you (specific milestones, not vague “growth”).
- A downside plan that is operationally real (headcount, spend cuts, and a path to breakeven if needed).
In terms, the reset is simple: money still moves fast for companies that look inevitable, and it moves slowly for companies that look optional. If you’re in the optional bucket, optimize for survivability and leverage, not optics. That usually means raising enough to hit a specific inflection, keeping burn aligned to learning velocity, and avoiding term structures that remove control when growth comes in below plan.
If you’re already scaled, the key is protecting strategic freedom. A large round that forces unnatural spend can create a performance trap. A round that matches your actual distribution capacity keeps execution clean, keeps hiring standards high, and preserves optionality for M&A, secondaries, or a later IPO window.
Where Does This Reset Go Next, And What Should You Do Monday Morning?
The next phase is continued concentration paired with selective reopening of exit routes. KPMG’s reporting shows exit value improved in 2025, and it expects solid VC investment heading into 2026, supported by improving conditions and investor confidence. That’s constructive, but it doesn’t bring back “anything goes” underwriting.
You should assume two truths at once. One: there is a lot of money in the system, and it will fund companies that show dominance and control. Two: fundraising remains harder than headlines suggest, since VC fundraising is still weak and LPs remain disciplined.
Monday morning priorities that match this market:
- Instrument the business so retention, margin, and payback are visible weekly, not quarterly.
- Rebuild the plan with a base case that works without perfect conversion rates and without surprise hiring.
- Audit your growth spend and cut anything that does not show a tight link to payback.
- Decide your financing posture: raise now with clear milestones, run to profitability, or pursue strategic capital if your cost structure demands scale.
If you do those four things, the reset stops being a threat and becomes an advantage. Many competitors will keep operating with 2021 assumptions. A controlled operator wins share when others chase vanity metrics.
What Does “The Great VC Reset” Mean For Founders?
- Capital concentrates in fewer winners
- Fundraising takes longer
- Efficiency metrics matter more than hype
- Credible exit paths drive valuations
Turn This Reset Into Leverage
You don’t need a softer market to build a venture-scale company, you need control: control of burn, control of retention, control of margins, and control of your narrative with investors. The data points are consistent: fundraising is tighter, capital is concentrating, and AI-driven megadeals skew the headlines. Your job is to build a company that still wins when the fundraising environment is selective, the time-to-liquidity is longer, and investors reward execution over promises. Tighten the operating system, set milestones you can actually hit, and raise only when the next check increases strategic freedom rather than forcing artificial speed.